Women’s retirement income gap narrows slightly
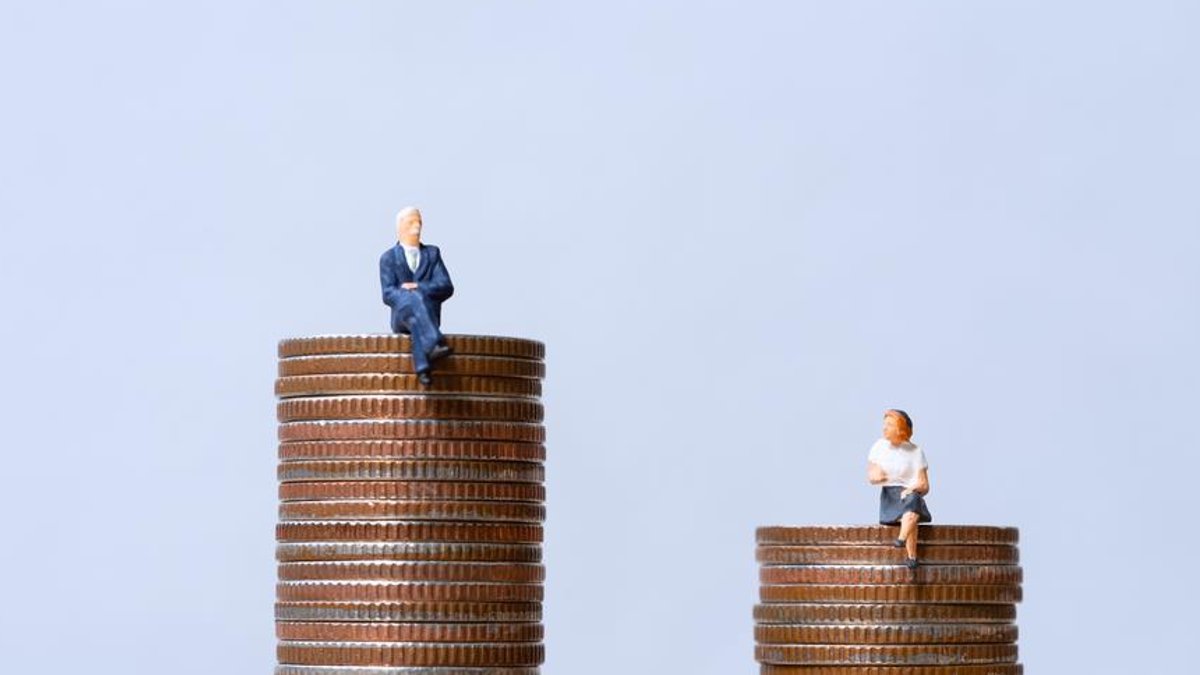
The difference between projected retirement incomes for men and women has shrunk to £3,800 annually, a reduction from £6,000 in 2025 and £7,000 in 2023, according to the latest findings from Scottish Widows’ 2026 Women and Retirement Report.
Women now expect a median annual retirement income of £14,500, up £1,500 from previous estimates, while men’s projections stand at £18,300. This shift reflects closing gender pay disparities, increased state pension entitlements, and greater savings accumulation. Still, the disparity in median defined contribution pension pots between genders remains significant at £95,000.
Despite these improvements, financial security in retirement remains precarious for many women. Sixty-five percent are on track for only a basic standard of living, with one-third (33%) facing potential retirement poverty. Only 27% are expected to achieve a comfortable retirement lifestyle.
Closing the Gender Pension Divide
Jill Henderson, head of workplace strategic relationships at Scottish Widows, said: “The fact that the gender pension gap is at its narrowest point since the National Retirement Forecast began is proof that progress is possible.
“Too many women face a retirement of financial hardship… Understanding how long-term savings are tracking is essential to helping women stay financially secure.
Unpaid Care’s Financial Toll
The report examines how unpaid caregiving responsibilities affect retirement savings, estimating that women working reduced hours to accommodate adult care could forfeit £220 million in annual pension contributions.
Among women providing adult care, 27% temporarily left employment due to difficulties finding affordable or suitable care arrangements, while 14% reduced their working hours. Of those who exited the workforce, one in five (20%) remained out of employment for at least a year.
Read Also: Indian brands face rising raw material costs
Scottish Widows calculates that these employment gaps could result in £5.9 billion in lost pension contributions if unpaid, based on current salary and contribution levels.
Life Transitions and Retirement Planning
Other significant life events also influence women’s ability to save for retirement, including menopause and divorce. Nearly three in ten (29%) women experiencing menopause symptoms reported negative effects on their retirement savings, while 25% of divorced women said their retirement planning had worsened.
During separations, 24% of divorced women said pensions were never discussed, and only 16% had pensions addressed through sharing, offsetting, or combined approaches.
Scottish Widows urged employers to use workforce and pension data to identify differences in participation and contributions by gender, age, earnings, and working patterns.
The report also highlights limited awareness of National Insurance credits, which safeguard carers’ state pension benefits. Only 39% of women currently providing regular adult care have heard of these credits, and just 11% have claimed or received them.
Scottish Widows suggests that changes – such as parental leave, reduced hours, and returning to work – trigger support to help employees understand and rebuild their pension savings.
An analysis of Lloyds Banking Group customers with regular payroll income found that 14% of women under 30 earned below the £10,000 automatic enrolment threshold, compared with 9% of men.


