Toronto and Vancouver no longer top housing bubble risks
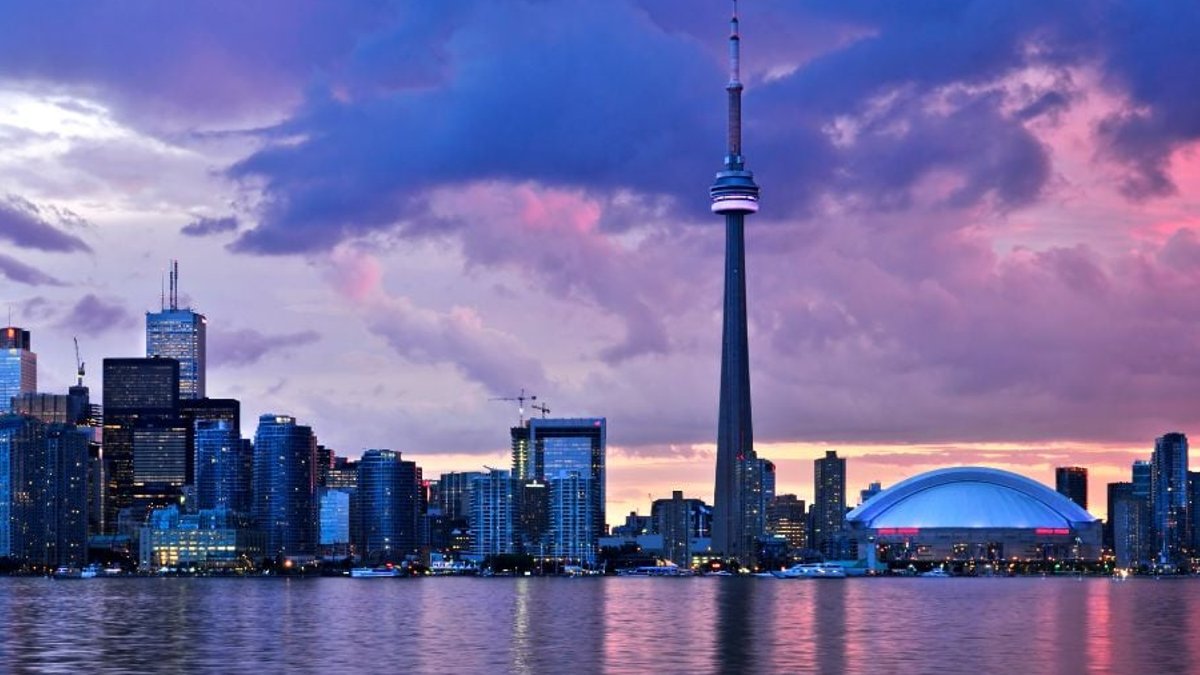
Toronto and Vancouver have moved out of the highest-risk category for housing bubbles after sustained price declines and raised financing costs, according to UBS’s 2026 Global Real Estate Bubble Index. The two cities now fall into a moderate-risk tier, having lost their top spots in earlier assessments.
Global Index Highlights Top Risks
The 2026 Global Real Estate Bubble Index evaluated 23 cities worldwide, identifying Zurich and Tokyo as the most vulnerable to bubble conditions. Other markets at raised risk include Miami, Dubai, Seoul, Geneva, and Lisbon. Toronto and Vancouver, which had led bubble-risk rankings in 2021, have each recorded real house price declines of approximately 10% over the past year.
UBS economists attribute the shift to higher-for-longer financing costs, which are likely to cap house-price gains in the near term. “Higher-for-longer financing costs are likely to cap house-price gains in the near term,” said Matthias Holzhey, lead author of the study and economist at UBS Global Wealth Management’s Chief Investment Office. This adjustment follows a broader pattern: cities previously flagged for high bubble risk, such as Frankfurt, Paris, Toronto, Hong Kong, and Vancouver, saw average real price drawdowns of nearly 20% from their peaks as interest rates rose in subsequent years.
Read Also: Gen Z Canadians hit hardest by payment fraud
Royal LePage’s 2026 outlook predicts further declines in Canada’s largest markets. Home values in the Greater Toronto Area are projected to decrease 4.5% year-over-year to $1,054,129 by late 2026, while Greater Vancouver prices are expected to decline 3.5% to $1,147,868 in the fourth quarter of 2026. Those projections align closely with the trajectory the UBS index is tracking.
Policy Moves Dampening Canadian Markets
The shift reflects a confluence of policy interventions and macroeconomic conditions. Tougher rules from new taxes to outright purchase bans to rent control measures have dimmed the appeal of once sought-after markets such as Vancouver and Toronto, according to Maciej Skoczek, author of the study and economist at UBS Global Wealth Management’s Chief Investment Office.
Even with lower prices, affordability challenges persist. Across most cities analyzed, the annual ownership costs of a newly purchased 60-square-metre home—including mortgage interest and maintenance—exceed 40% of a highly skilled worker’s gross income. That affordability squeeze is directly relevant to advisors who are helping clients evaluate real estate as part of a broader investment portfolio. Even with price corrections in Toronto and Vancouver, entry costs remain prohibitive for many first-time buyers, keeping rental demand raised and sustaining the investment case for existing landlords, though with materially lower price growth expectations than in prior cycles.
Read Also: Visa Study: Consumers Demand Cheaper, Faster Global Money Transfers
Housing’s Mixed Role in Inflation
The index contradicts the traditional view that housing acts as an inflation safeguard. In over half of the cities analyzed, housing did not provide inflation protection over the last five years. Markets identified as being at high bubble risk in 2021 subsequently recorded the sharpest price declines, averaging roughly 15% since then. However, the outlook is less pessimistic on a forward-looking basis. Skoczek noted: “At current valuations, housing in most cities is nevertheless likely to provide inflation protection over the medium term.”
Inflation’s effects varied across markets. Cities with above-average inflation experienced average real house price declines of roughly 5%, while those with below-average inflation achieved average real annual price growth of around 10% over the same period. The data reveals a shift in Canada’s housing behavior, where steady price increases are no longer assured.
Wealth advisors should approach real estate investments with caution, according to the UBS report. While Toronto and Vancouver’s markets have cooled, affordability pressures and supply shortages remain. The analysis indicates that housing may offer inflation protection over the medium term, though the period of rapid price appreciation in these markets has passed, at least for now.


